Monday 28 / September / 2026
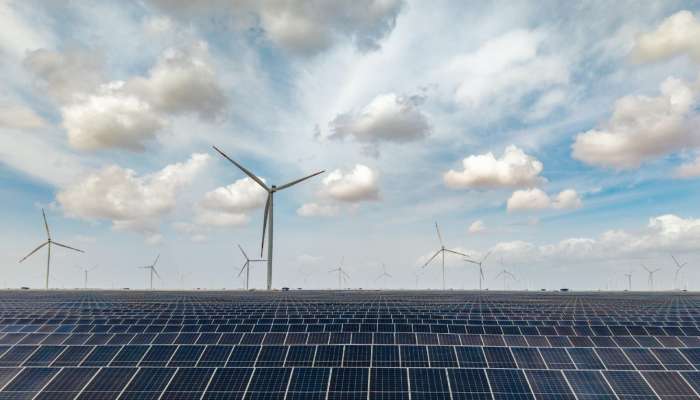
Solar manufacturing has emerged as a major success story for India. Investment in solar manufacturing has surged from just $85 million in 2018 to $12 billion in calendar 2025, followed by another $4 billion in the first half (H1) of 2026. In other words, $16 billion has been invested in the sector in just 18 months.
The pipeline of announced investments points to continued momentum. According to the Clean Investment Monitor report by the Rhodium Group, a US-based market research and analytics firm specialising in renewable energy, $16 billion worth of solar manufacturing investments were announced in 2025, followed by another $8 billion in H1 2026.
India’s manufacturing capacity has expanded dramatically over the past decade. In 2014, the country had around 2.5 GW of module manufacturing capacity and no cell manufacturing capacity. Today, according to the Rhodium Group, India has 242.7 GW of module capacity, 40.5 GW of cell capacity and 2.5 GW of wafer capacity. The significant gap between module and cell capacity remains a concern. However, with another 40 GW of cell capacity expected to come online — roughly half of it in 2026 — the imbalance should gradually narrow. In addition, 24 GW of wafer capacity has already been announced.
The principal driver of this expansion is clearly government policy. The mandate requiring solar projects to use domestically manufactured modules under the Approved List of Models and Manufacturers (ALMM), along with requirements covering cells, has provided manufacturers with a substantial captive market. The government is also working to extend the ALMM framework to wafers. The scope of the policy has been expanded to cover almost all solar projects in India, with limited exemptions, including certain net-metering and open-access projects that have been given a commissioning window until December 31.
India’s solar installed capacity now stands at around 168 GW and accounts for approximately 12 per cent of the country’s electricity generation.
The more troubling development is the new set of US trade measures. The US has been an important export market for some Indian solar manufacturers, but that market has effectively been closed off by two separate measures.
The first is the recent determination by the US Department of Commerce that imports from India, Laos and Indonesia should face anti-dumping and countervailing duties. For India, the applicable dumping margin has been set at 123.04 per cent, while the final cash-deposit rate for the countervailing duty, after accounting for subsidy offsets, is 107.17 per cent. The US International Trade Commission must still determine whether these imports have caused material injury to the domestic industry. If it finds that they have not, the deposits would be refunded.
The second measure involves tariffs imposed under Section 232 of the US Trade Expansion Act, which gives the US President the authority to restrict imports on national-security grounds. The measures establish two additional barriers: a 15 per cent ad valorem duty on specified polysilicon derivatives, along with minimum import prices of $21 per kg for polysilicon, $100 per kg for ingots and wafers, $0.22 per W for solar cells and $0.38 per W for modules.
In principle, these measures could have created an opportunity for Indian manufacturers in the US market by reducing the enormous price advantage enjoyed by Chinese suppliers and putting competing producers on a more level playing field. However, the anti-dumping and countervailing duties largely eliminate that opportunity.
This raises two important questions: What will be the impact on India, and can Indian manufacturers still find a way to access the lucrative US market?
The immediate impact on India is likely to be manageable. Indian exports of modules and cells to the US were worth around $1.2 billion last year, representing about 13 per cent of the value of modules and cells produced in the country. With access to the US market severely constrained, much of this output will have to find a home elsewhere, primarily in India.
The encouraging factor is the size and growth of the domestic market. There is little reason to assume that India cannot absorb the additional supply, although increased competition could put pressure on manufacturers’ margins. The disruption may therefore squeeze profitability without necessarily threatening the viability of the industry.
As for maintaining access to the US market, one potential route is for Indian companies to establish manufacturing facilities in the United States. The US continues to encourage foreign investment in solar manufacturing. Some Indian companies, including Waaree and Inox, already have a presence in the US, while Premier Energies has indicated that it is interested in establishing manufacturing facilities there. However, there does not appear to be a strong appetite among Indian manufacturers to make such a move. Several companies have indicated that setting up operations in the US would be challenging.
There is another, potentially more immediate opportunity. Indian manufacturers that move quickly into ingot and wafer production could find a niche in the US market, where there is currently a shortage of non-Chinese wafers. It could take time for US manufacturers to bridge this supply gap.
Indosol Solar, a subsidiary of Shirdi Sai Electricals, has said that its ingot and wafer plant is expected to be commissioned soon and that it is hopeful of exporting to the US. For Indian manufacturers, therefore, the US market may not be entirely closed — but accessing it could increasingly require manufacturing on American soil or concentrating on segments where non-Chinese supply remains scarce.